FIRST$AVER

A youth banking account for SC Mobile, Standard Chartered Singapore

A youth banking account for SC Mobile, Standard Chartered Singapore

Release Date

2024

Client

STANDARD CHARTERED BANK
STANDARD
CHARTERED BANK

Role

Role

Lead Designer

Product Duration

Product Duration

9 - 10 MONTHS

role

LEad Designer

Product Duration

9 - 10 MONTHS

Most children in Singapore will make their first payment before they ever hold a paycheque. First$aver is a joint account built for that reality:

the child gets a bank account that actually feels like theirs, the parent gets to watch, top up, and set the guardrails. I designed the full

post-onboarding experience for both parent and child, from first sketches in January to the October launch,

while a second designer owned the sign-up journey.

Most children in Singapore will make their first payment before they ever hold a paycheque. First$aver is a joint account built for that reality: the child gets a bank account that actually feels like theirs, the parent gets to watch, top up, and set the guardrails. I designed the full post-onboarding experience for both parent and child, from first sketches in January to the October launch, while a second designer owned the sign-up journey.

Most children in Singapore will make their first payment before they ever hold a paycheque. First$aver is a joint account built for that reality: the child gets a bank account that actually feels like theirs, the parent gets to watch, top up, and set the guardrails. I designed the full post-onboarding experience for both parent and child, from first sketches in January to the October launch,

while a second designer owned the sign-up journey.

oct 2024

Launched on SC Mobile for Singapore families, with instant account opening via MyInfo.

Launched on SC Mobile

for Singapore families,

with instant account

opening via MyInfo.

Launched on

SC Mobile for Singapore families, with instant account opening via MyInfo.

S$100 a day

S$100
a day

Low default limits on card

spend and transfers. Protection designed into the defaults.

Low default limits on card spend and transfers. Protection designed

into the defaults.

Low default limits

on card spend and transfers. Protection designed into

the defaults.

two users

One account serving a child

learning independence and

a parent needing oversight.

One account serving a child learning to be independent and a parent needing oversight.

One account serving a child learning to be independent and

a parent needing oversight.

So how do we design one product

for a customer who has never

banked before, and their parent

who worries about exactly that?

SO HOW DO WE Design

one product for

a customer who

has never banked before, and their parent who worries about exactly that?

SO HOW DO WE Design one

product for a customer who

has never banked before, and their parent who worries

about exactly that?

SO HOW DO WE Design one product for a customer who has never banked before, and their parent who worries about exactly that?

To respect confidentiality obligations to Standard Chartered Bank, some details in

this case study have been omitted or generalised. All views expressed here are my own.

To respect confidentiality obligations to Standard Chartered Bank, some details

in this case study have been omitted

or generalised. All views expressed

here are my own.

To respect confidentiality obligations to Standard Chartered Bank,

some details in this case study have been omitted or generalised.

All views expressed here are my own.

01

//Context

First$aver

//Context

First$aver

01

//Context

First$aver

A first account for kids who may never touch cash

A first account for
kids who may never touch cash

A first account for kids
who may never touch cash

A seven-year-old in Singapore today may never queue at a bank, never fill a deposit slip, never count change. Money arrives on cards and moves through QR codes. But the accounts banks offered families hadn't caught up: built decades ago around a parent and a passbook, they treated the child as a name on a form rather than a customer. First$aver set out to close that gap, giving kids a genuine first banking experience and giving parents a reason to trust it.

How pocket money moved from cash in hand to digital payments over a generation.

How pocket money moved from cash in

hand to digital payments over a generation.

02

//The Problem

First$aver

//The Problem

First$aver

02

//The Problem

First$aver

One product that gives the child independence
and the parent control.

One product that gives the
child independence and
the parent control.

A twelve-year-old and their parent open the same app wanting different things. The child wants to feel trusted: their own balance, their own card, money that responds to them. The parent wants to know nothing can go wrong: every transaction visible, every limit set, savings that a scammer or a moment of impulse cannot empty.

How do we make a child's first banking

experience feel like theirs, when it legally

and practically belongs to both?

How do we make

a child's first banking experience feel like theirs,

when it legally

and practically

belongs to both?

How do we make a child's first

banking experience feel like theirs,

when it legally and practically belongs to both?

How do we make a child's first banking experience feel like theirs, when it legally and practically belongs to both?

And it all had to live inside SC Mobile. One app, serving a first-time

banker and a veteran of it, without becoming two products.

And it all had to live inside SC Mobile. One app, serving a first-time banker and a veteran of it, without becoming two products.

What the child and the parent each needed from the same account.

What the child and the parent each

needed from the same account.

03

//Process

First$aver

//Process

First$aver

Starting with the apps kids were already using

Starting with the apps kids
were already using

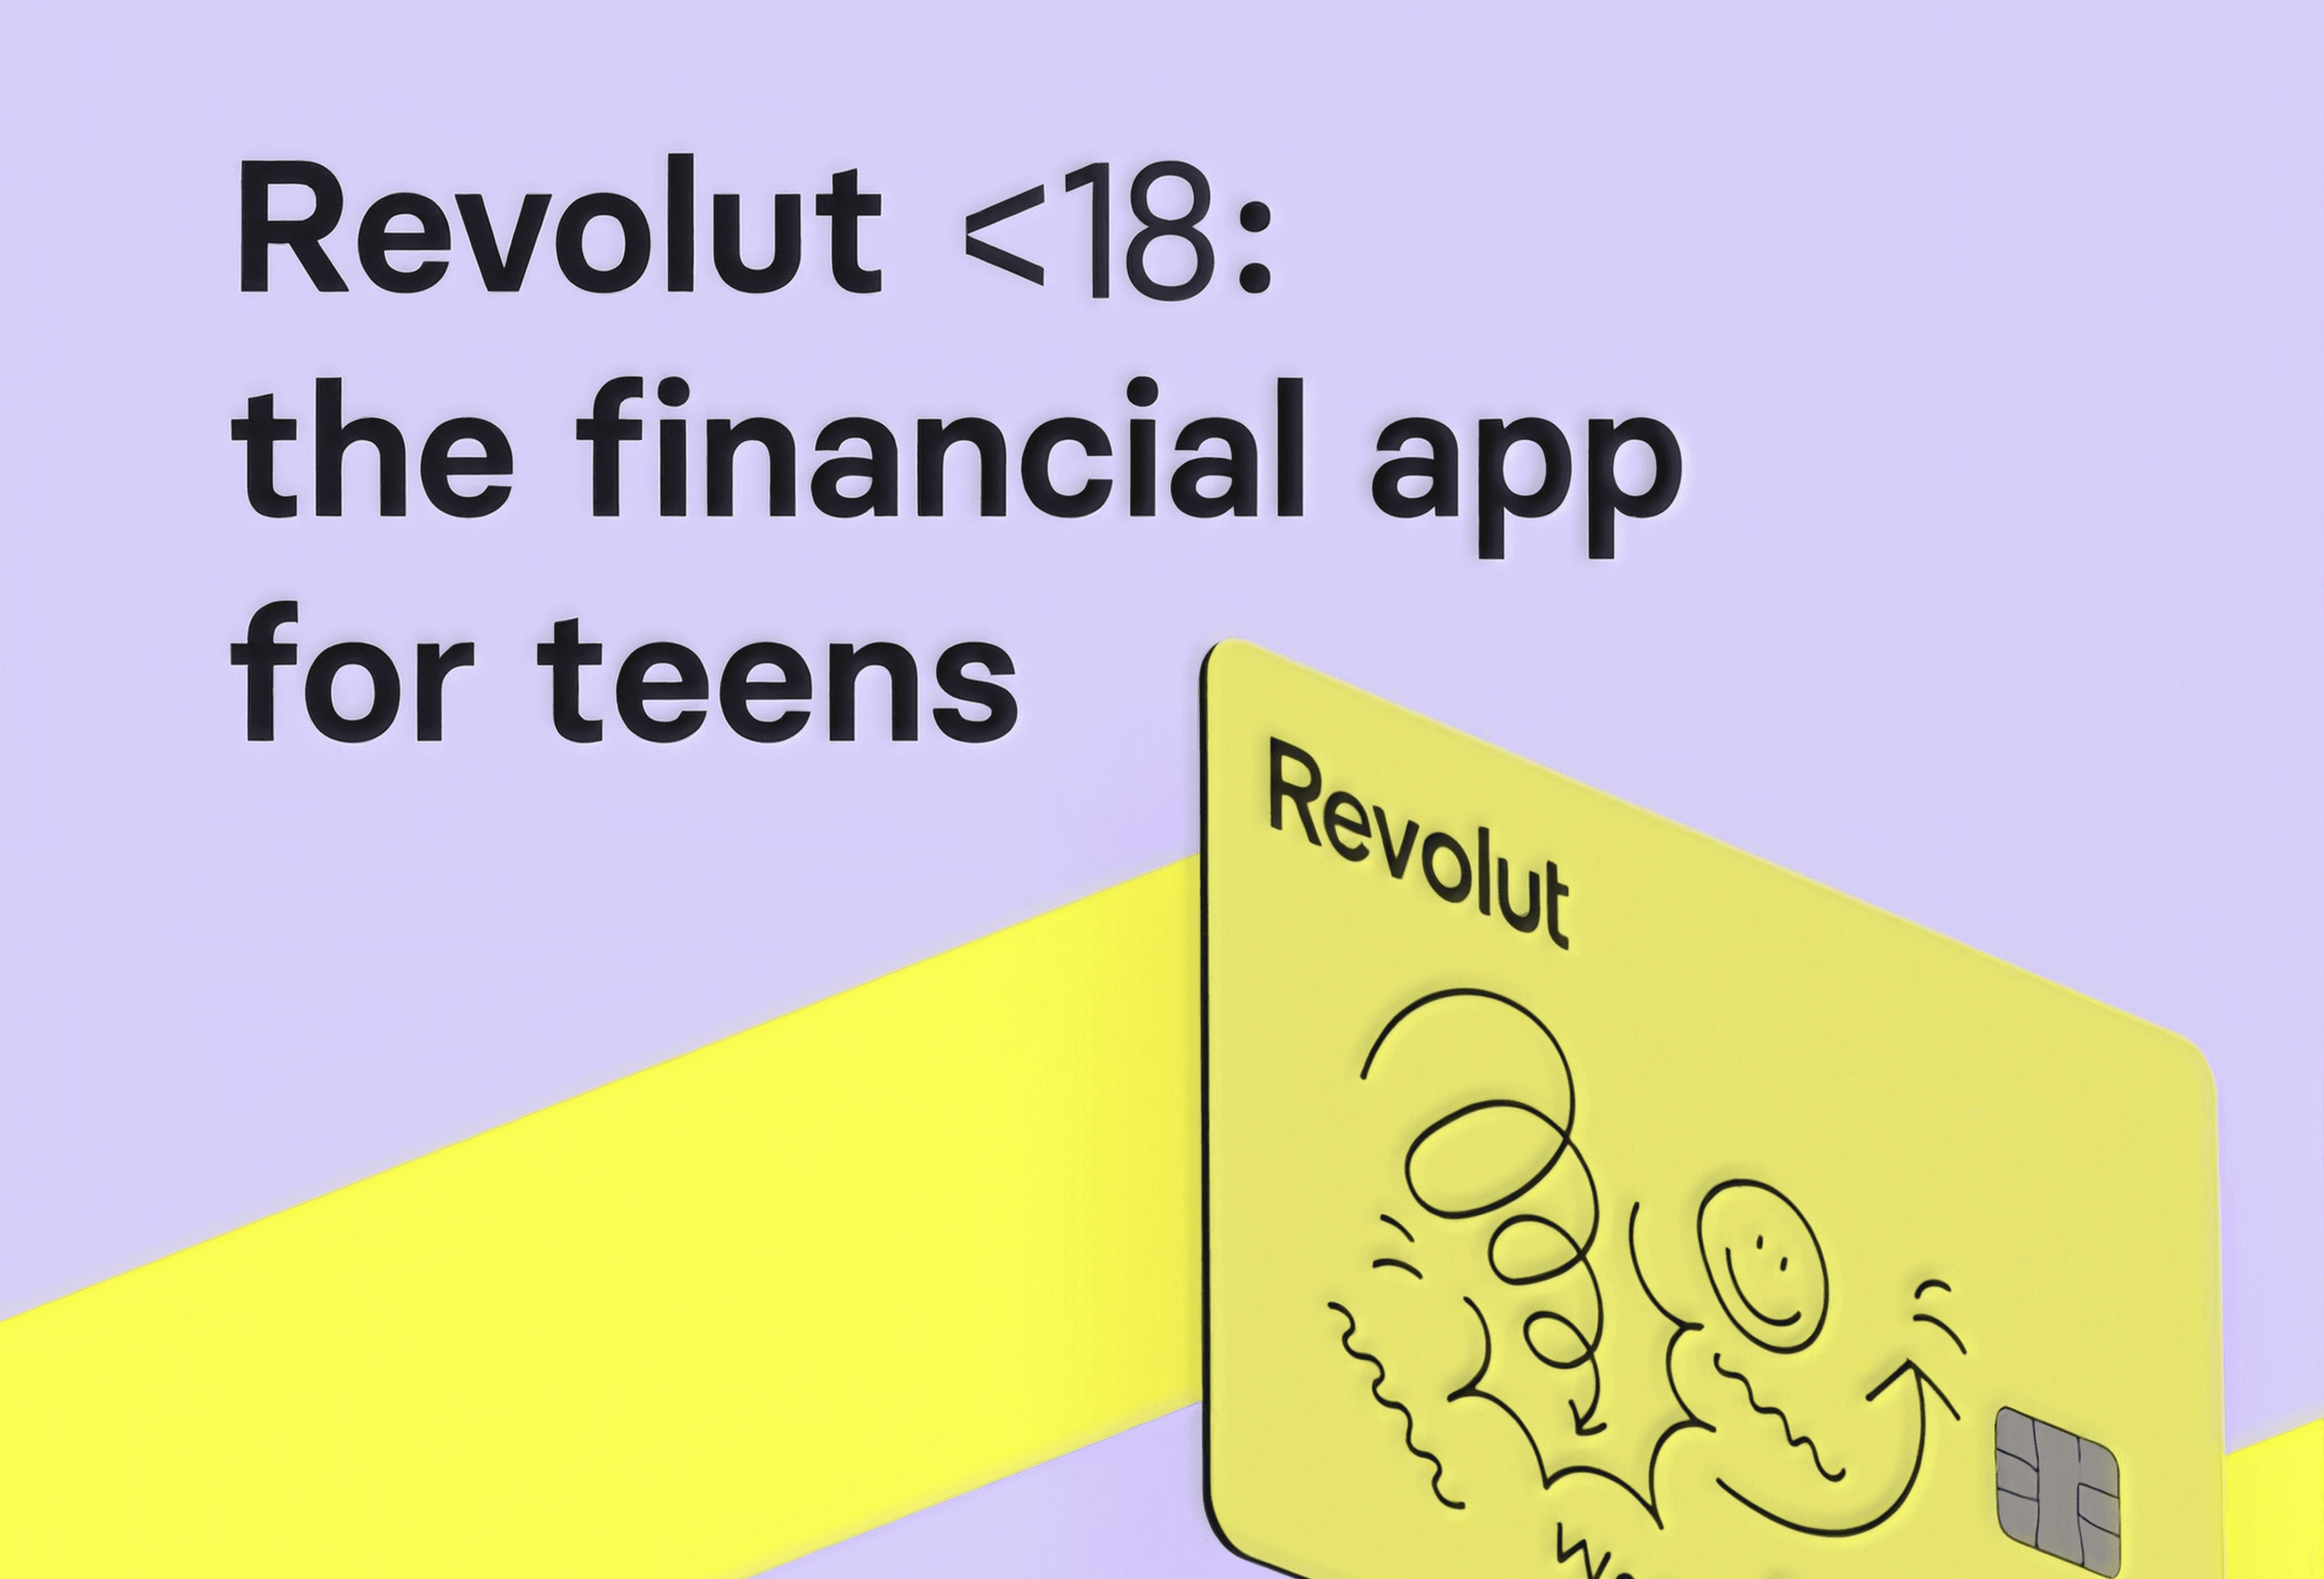
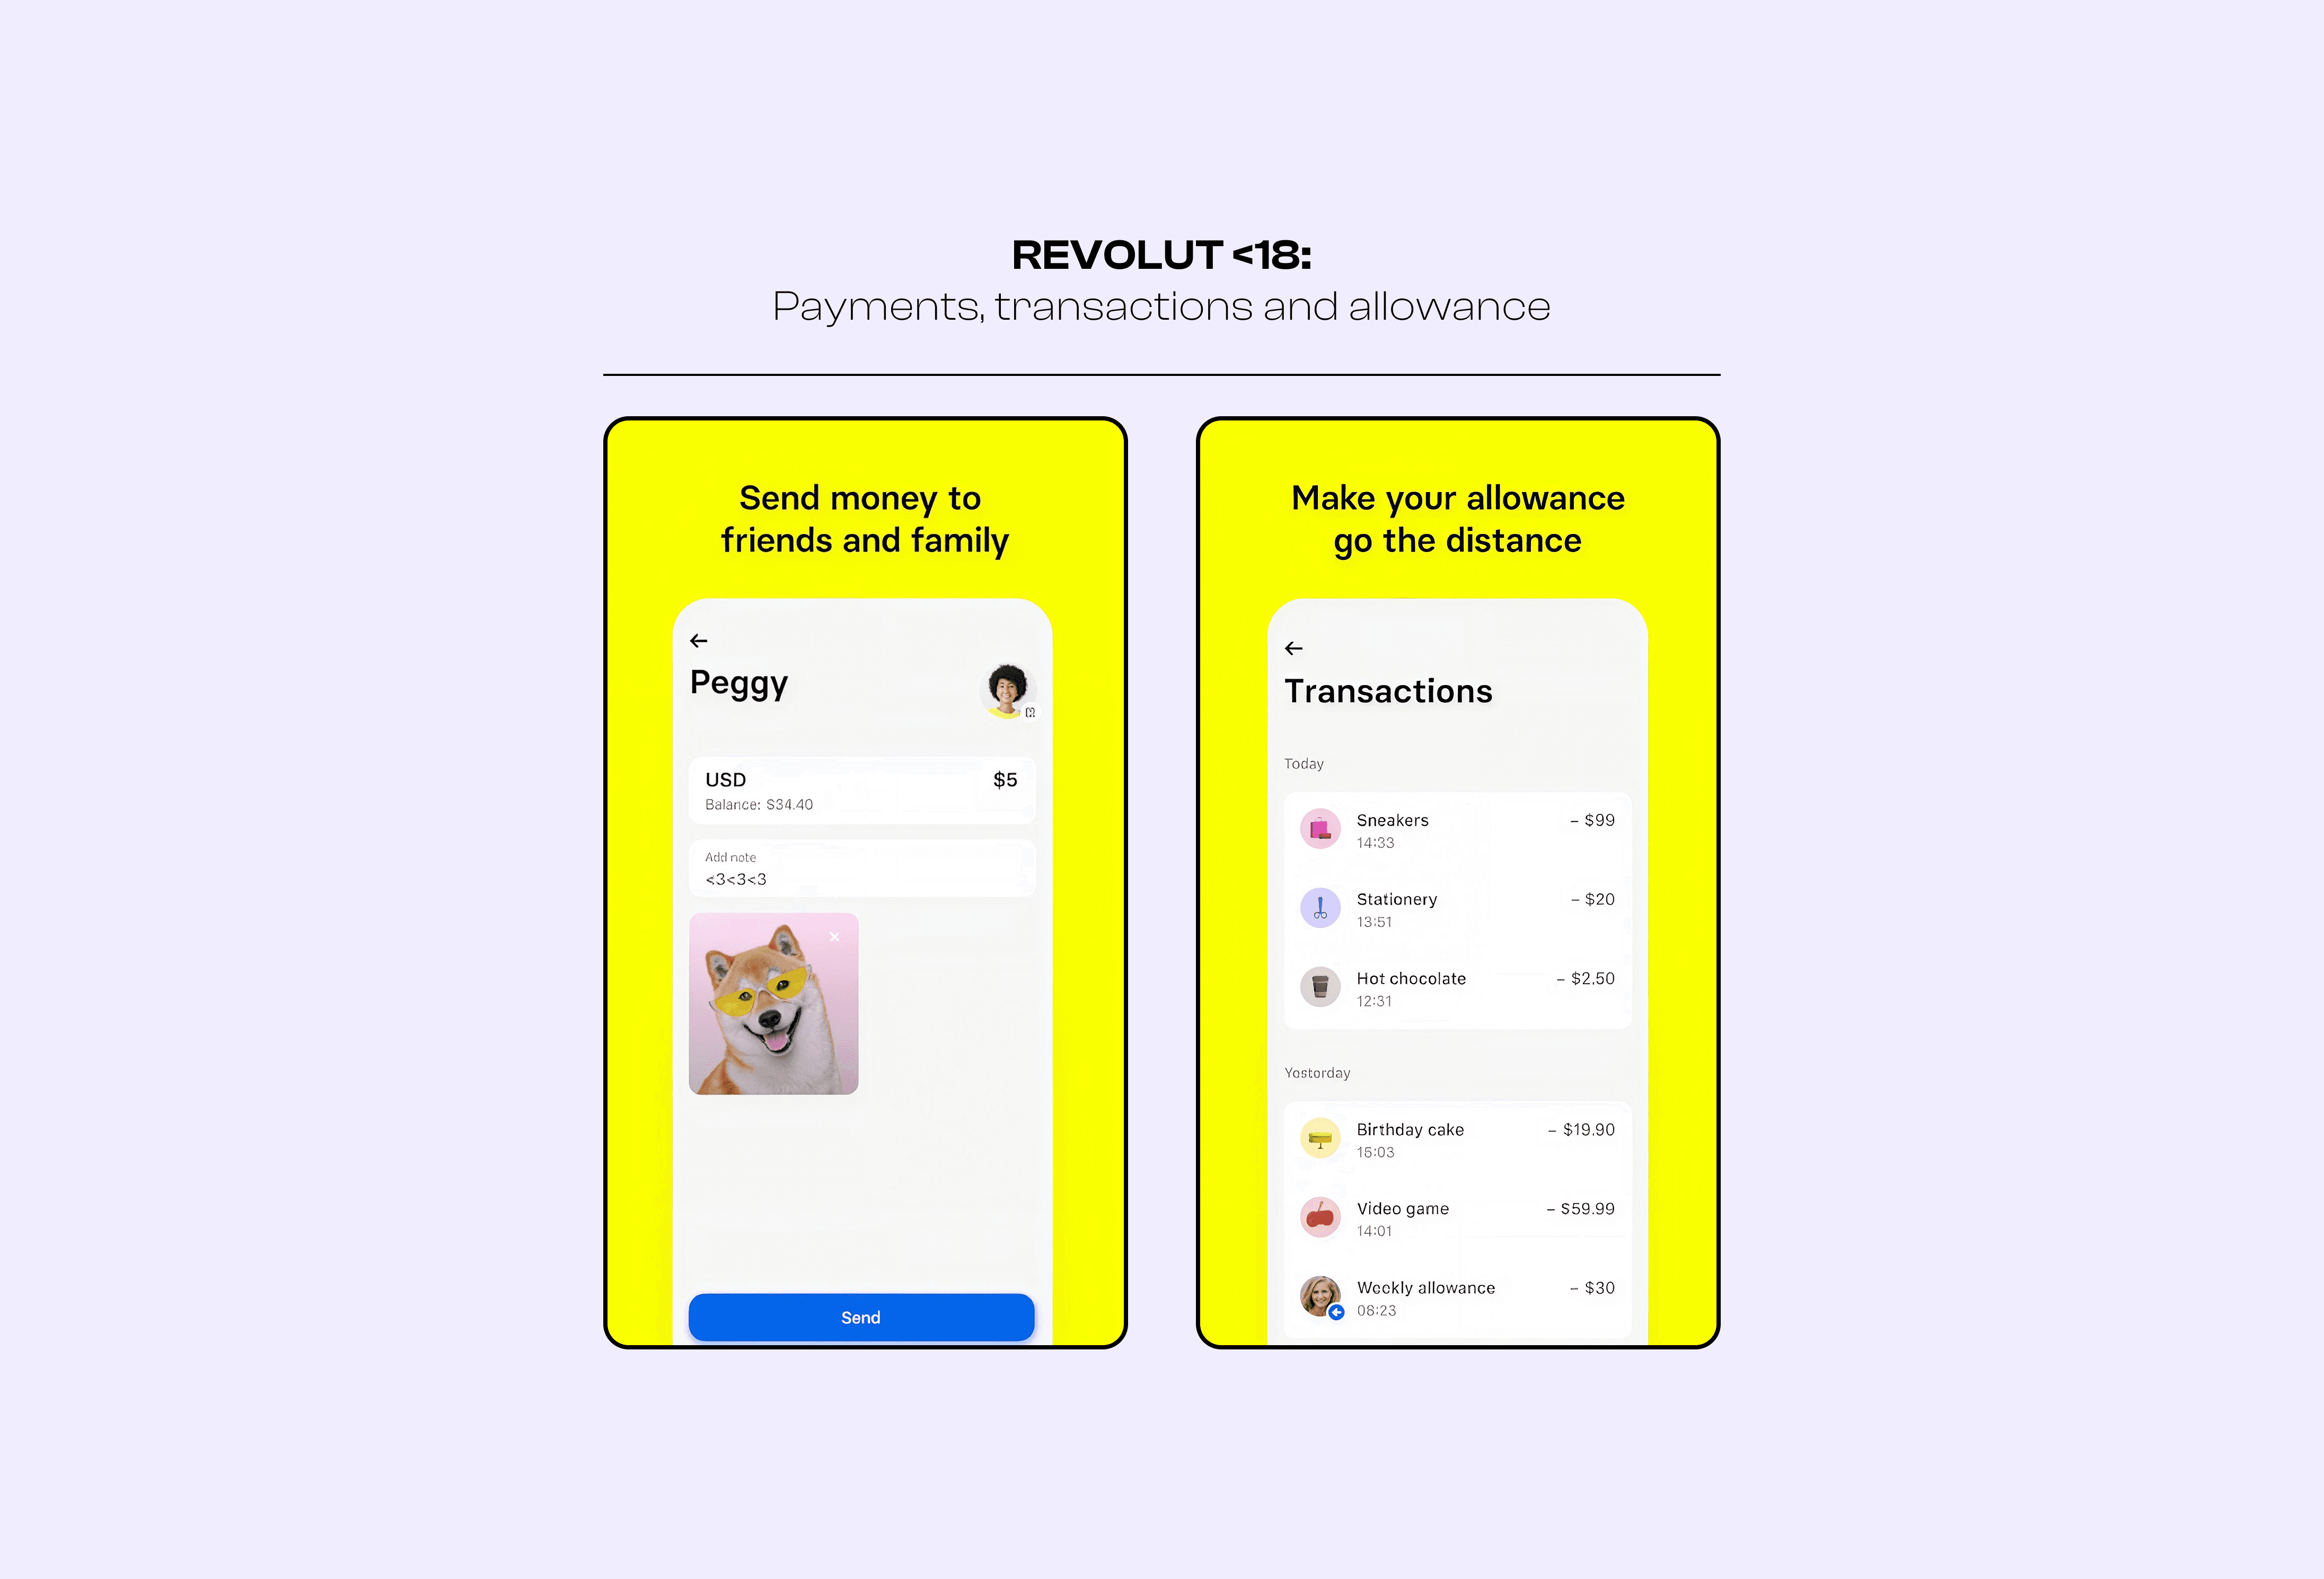
The work started with visual research into two products that had already put banking in young hands: POSB Smart Buddy and Revolut's Kids & Teens account. I studied how each designed for a young user: how Smart Buddy turned school pocket money into something a child tracks and saves through the app, and how Revolut built an experience where the child, not the parent, is treated as the primary user.


They marked out two very different answers. First$aver's answer would be different again: not a separate kids' app, but the same SC Mobile experience, simplified and quietened down for a first-time banker, with the parent keeping full oversight from their own app.

  • Discover
  • Learn
  • Lock
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage

How POSB Smart Buddy and Revolut Kids & Teens each hand banking to a child, from allowance to savings.

  • Discover
  • Learn
  • Lock
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage

Competitive analysis across three banks

that launched MoneyLock ahead of us.

  • Discover
  • Learn
  • Lock
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage

How POSB Smart Buddy and Revolut Kids & Teens each hand banking to a child, from allowance to savings.

  • Discover
  • Learn
  • Lock
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage

How POSB Smart Buddy and Revolut Kids & Teens each hand banking to a child, from allowance to savings.

Exploring what savings goals could look like

From there I went deeper on the feature I cared most about: savings goals. I ran a UI study across goal-tracking patterns, from banking apps to explorations on Dribbble, looking at how a goal could feel playful rather than transactional: progress you can watch, milestones worth celebrating, goals with names like a bicycle or a class trip. The study explored how far colour, illustration and motion could go for a young user while keeping the trust cues a parent expects from a bank.


From this research I conceptualised the goals journey and the kids' home screen, a quieter, pared-back take on the SC Mobile home, then designed the full post-onboarding account experience, both sides: the parent's oversight of transactions, top-ups and Money Lock, and the child's view of their balance, transactions and card. The goals designs made it to the finish line. The development timeline didn't, and goals were cut from MVP1.


Cutting a finished feature is its own kind of design work. The youth experience had been composed around goals as its heartbeat, so I rebalanced it around what remained: savings you can see, transactions you can follow, a card that's really yours. Nothing in the shipped journey could hint at the feature that wasn't there.

  • Discover
  • Learn
  • Lock
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage

The visual research behind the goals design: how progress, named goals and playfulness are handled across the industry.

  • Discover
  • Learn
  • Lock
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage

The visual research behind the goals design: how progress, named goals and playfulness are handled across the industry.

  • Discover
  • Learn
  • Lock
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage
  • Manage

The visual research behind the goals design: how progress, named goals and playfulness are handled across the industry.

04

//My Role

First$aver

//My Role

First$aver

One account, two journeys after the sign-up

My scope on First$aver began where onboarding ended: once a parent had opened the account, everything both users see and do was mine to design. That meant two of everything: two home experiences, two mental models, two definitions of success.

I mapped the parent's journey across allowance top-ups, transaction monitoring, and locking their child's savings with Money Lock to protect them from scams; and the youth's journey from receiving their card to spending and tracking on a simplified SC Mobile interface. I carried both through stakeholder reviews, compliance, and handoff to build, aligning with a second designer who owned the new-to-bank and existing-customer onboarding journeys that bring parents into the product.

05

//The Design

First$aver

//The Design

First$aver

Three decisions that

made two users possible

Three decisions

that made two

users possible

Three decisions that made two users possible

Lean Journey
Kids' View:
Banking, Simplified

A first banker doesn't need less banking, just less noise. The youth interface strips SC Mobile to

what matters at thirteen: my money, my card, my payments. Real capability, sized to

a first account.

A first banker doesn't need less banking, just less noise. The youth interface strips SC Mobile to what matters at thirteen: my money, my card, my payments. Real capability, sized to

a first account.

A first banker doesn't need less banking, just less noise. The youth interface strips SC Mobile to what matters

at thirteen: my money, my card, my payments.

Real capability, sized to a first account.

Locked State
Parents' View:
Full Oversight

Parents never leave their own app. Their child's transactions,

top-ups, and safeguards sit

inside the SC Mobile they

already know. Trust the child

with more; never ask the

parent to see less.

Parents never leave their own app. Their child's transactions, top-ups, and safeguards sit inside the SC Mobile they already know. Trust the child with more; never ask the

parent to see less.

Parents never leave their own app. Their child's transactions, top-ups, and safeguards sit inside

the SC Mobile they already know. Trust the child

with more; never ask the parent to see less.

Unlock
Safety
by Default

S$100 daily limits on spending

and transfers come switched on, not offered. Money Lock

ring-fences the savings. A first account should be the safest one

a person ever holds, before anyone configures anything.

S$100 daily limits on spending

and transfers come switched on, not offered. Money Lock

ring-fences the savings. A first account should be the safest one a person ever holds, before anyone configures anything.

S$100 daily limits on spending and transfers come switched on, not offered. Money Lock ring-fences

the savings. A first account should be the safest one

a person ever holds, before anyone configures anything.

  • Discover
  • Learn
  • Lock
  • Manage

The three decisions as they shipped: the kids' view, the parents' view, and the safeguards between them.

  • Discover
  • Learn
  • Lock
  • Manage

The three decisions as they shipped: the kids' view, the parents' view, and the safeguards between them.

  • Discover
  • Learn
  • Lock
  • Manage

The three decisions as they shipped: the kids' view, the parents' view, and the safeguards between them.

  • Discover
  • Learn
  • Lock
  • Manage

The three decisions as they shipped: the kids' view, the parents' view, and the safeguards between them.

06

//Outcome

First$aver

//Outcome

First$aver

A first bank account that grows with the child

A first bank account
that grows with the child

First$aver went live in October 2024, opening in minutes through MyInfo. It was built to grow up alongside its owner: the card, cashback, and mobile access switch on at thirteen, so the account opened for a primary schooler quietly becomes a teenager's daily bank.

What stays with me from this project is the discipline of the cut. Finished designs are not shipped designs, and when goals fell out of MVP1 my job became making the smaller product feel whole rather than mourning the bigger one. The goals work is done and waiting, and it's the feature I'd fight for in MVP2: a balance teaches a child what they have, but a goal teaches them what saving is for.

Let'S WORK

TOGETHER

Man
OPEN TO SENIOR EXPERIENCE DESIGNER ROLES AND
FREELANCE UI/UX AND LOGO DESIGN PROJECTS.

Let'S WORK

TOGETHER

Man
OPEN TO SENIOR EXPERIENCE DESIGNER
ROLES AND FREELANCE UI/UX AND LOGO
DESIGN PROJECTS.